June 8, 2026 · Market Report
Originally shared with Elev8 Realty Group clients on June 8, 2026.
Seattle’s Spring Market Kept Its Promise. The June Numbers Point to a Slower Summer.
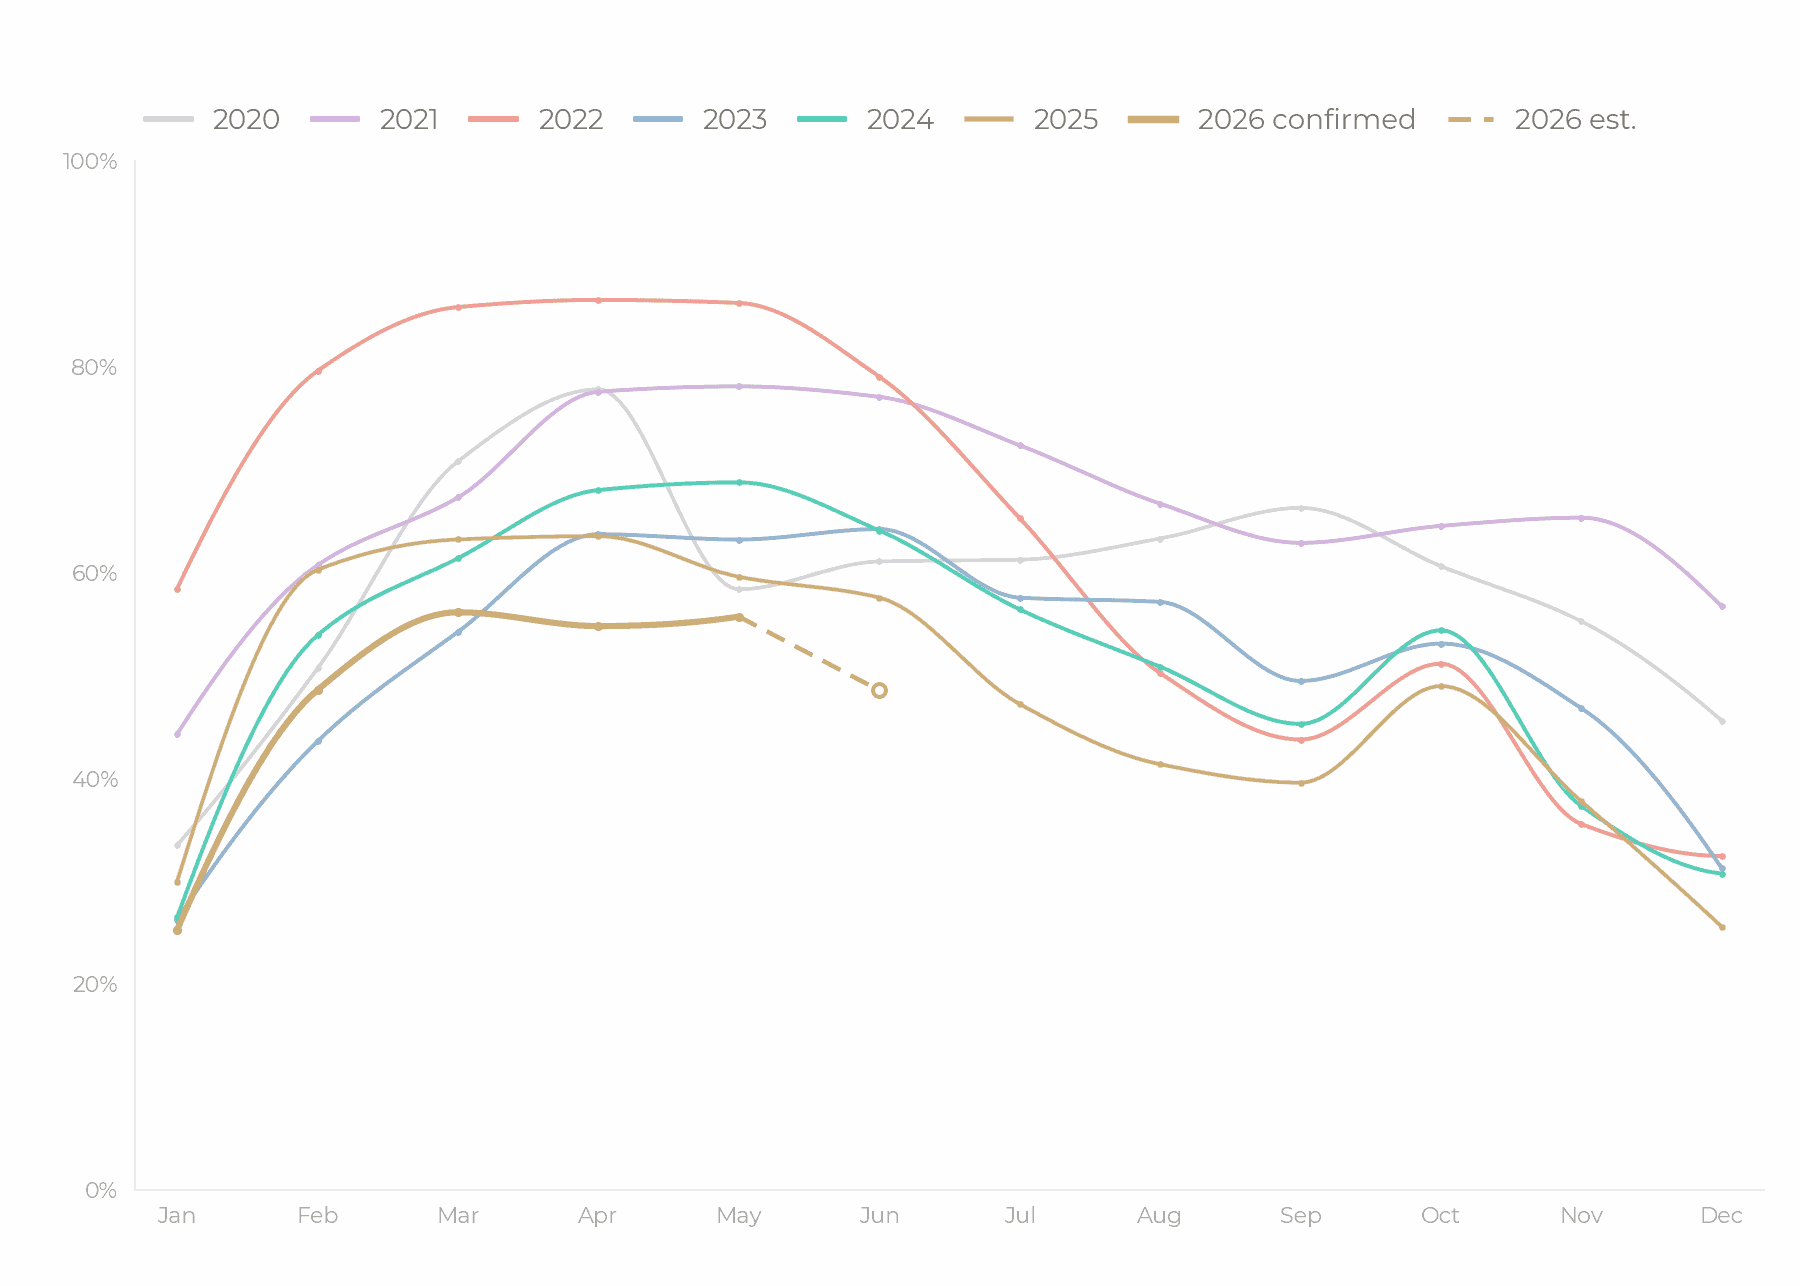
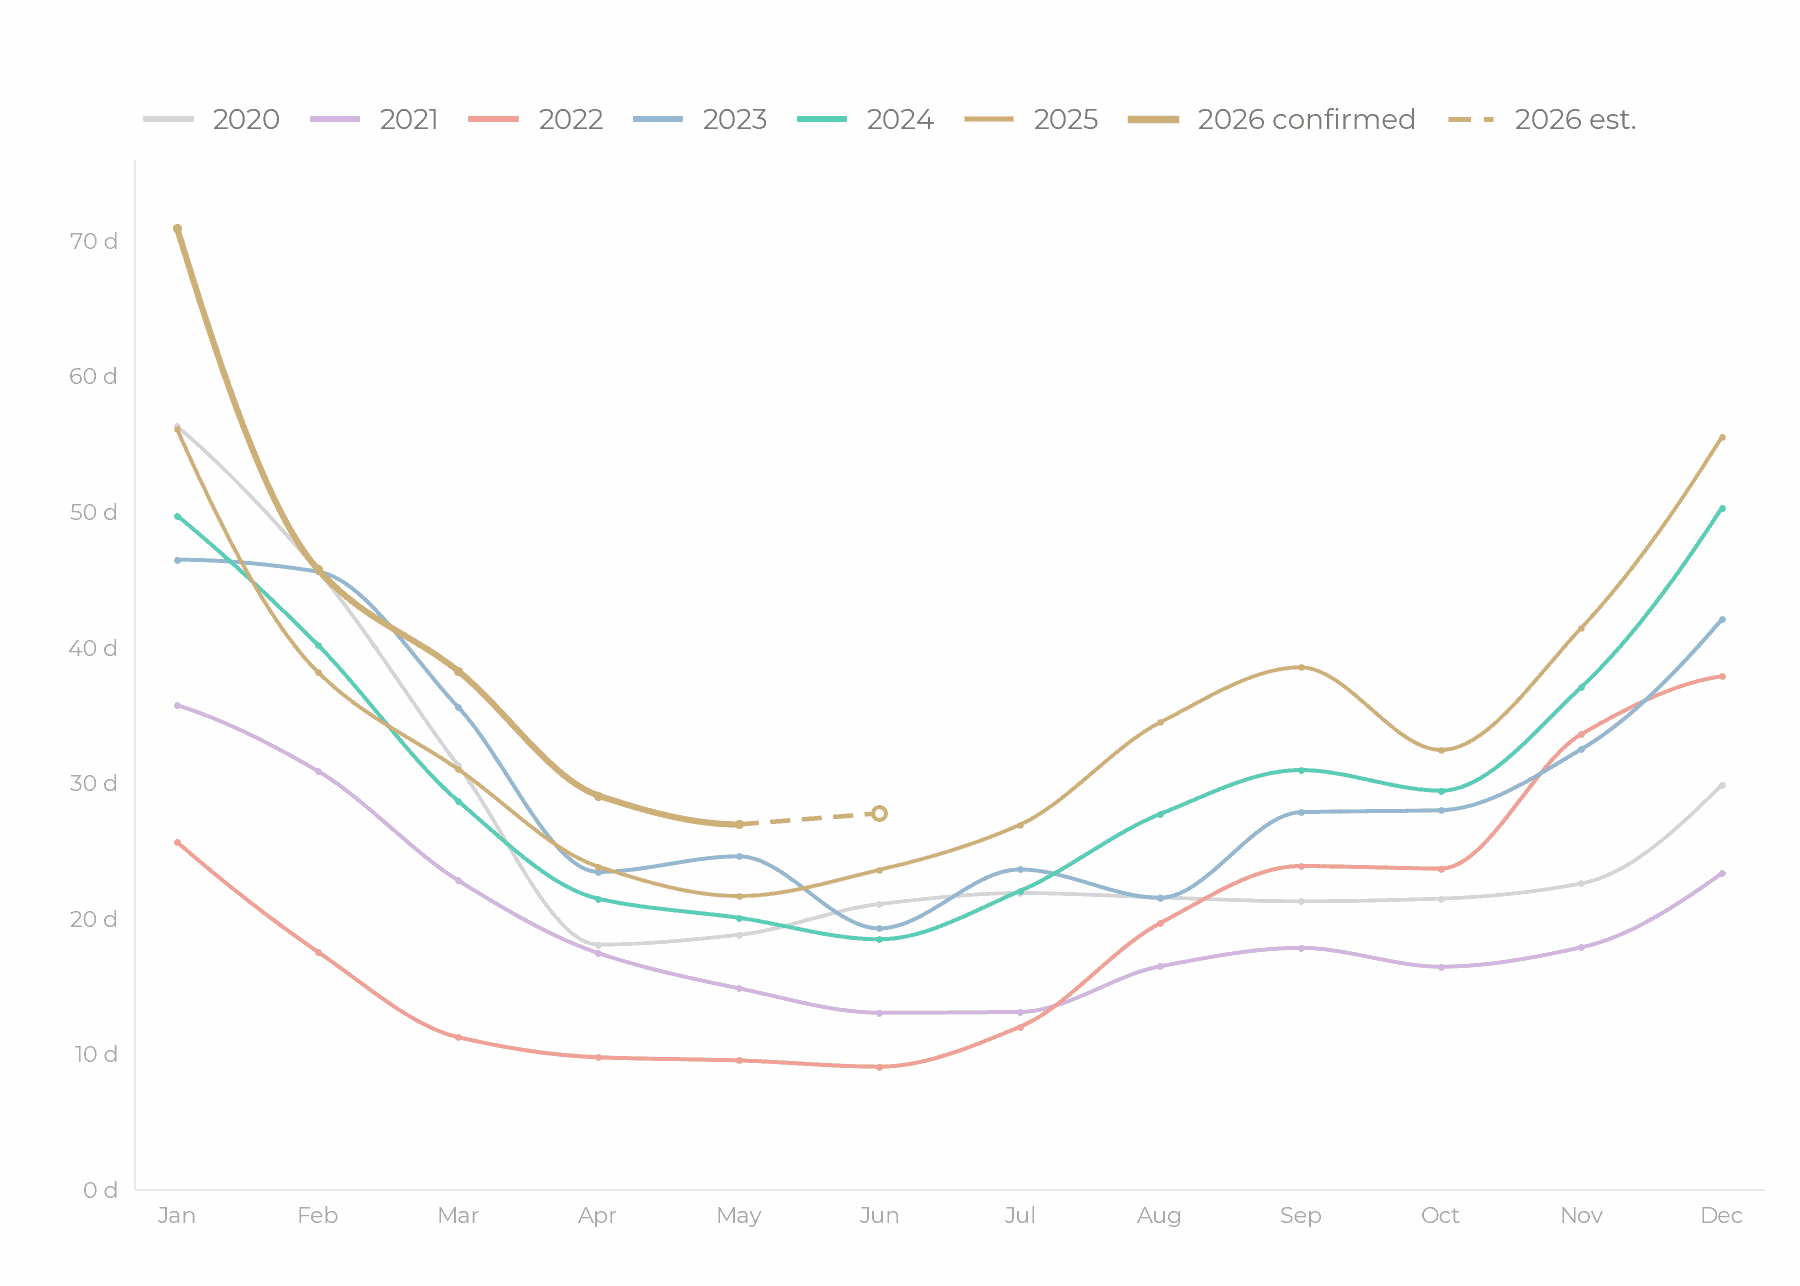
May behaved. More than half of the homes that sold in our Seattle selection went under contract inside their first ten days, three quarters sold within a month, and the average sale still closed a point above asking. Days on market came in just under 27, the fastest of the year so far. Last month our leading data projected May at +1.7% on the Market Pulse and the confirmed reading landed at +1.3%, close enough, but softer enough to notice and stay alert on what is ahead.
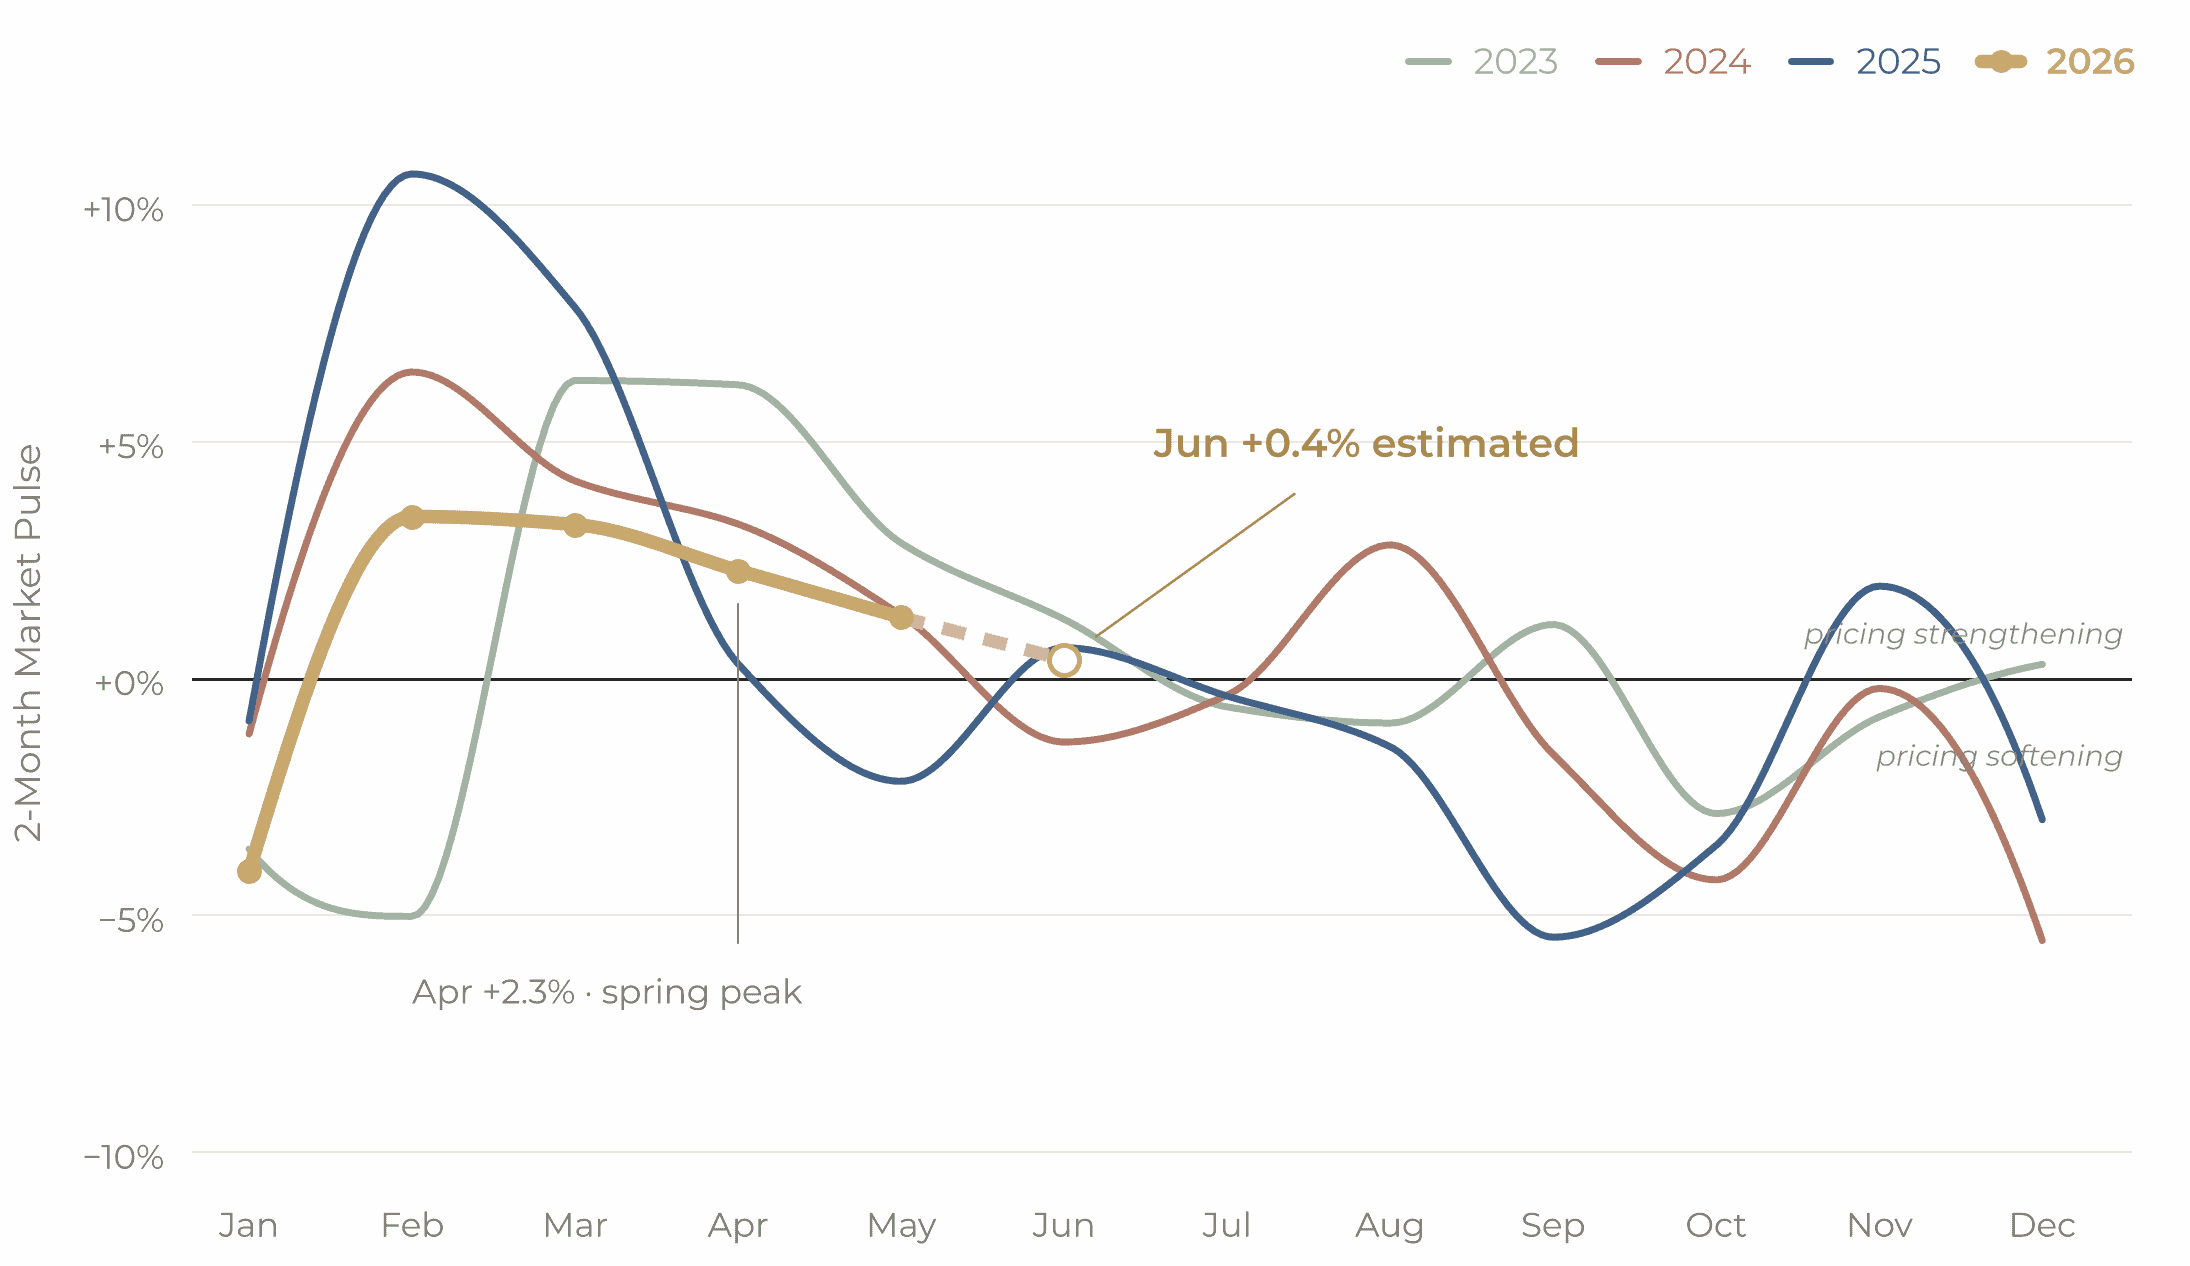
The noticing matters because of the shape of the line. April confirmed at +2.3%, May at +1.3%, and the early read on June sits at +0.4%. Momentum is still positive. It is also clearly decelerating, and it has decelerated in almost exactly this pattern in four of the past five years as spring urgency burns off into summer. Nothing in the data says this year is different. What the data can’t tell me yet is whether this is the normal seasonal exhale or the start of something with more weight behind it, and I’d rather admit that than pretend the chart speaks more clearly than it does. June’s confirmed numbers will settle it.
Friday Took Rate Relief Off the Table
The macro story of the month is the jobs report. The economy added 172,000 jobs in May against expectations of roughly 100,000, the third straight month of six-figure gains, and the prior two months were revised up on top of it. Good for paychecks. Inconvenient for anyone waiting for lower interest rates because a labor market this sturdy while inflation runs at double the Fed’s target has once again flipped the bond market conversation from when they cut to whether they hike.
Mortgage rates heard it. The 30-year fixed touched 6.35% in late May and has been climbing back toward 6.5% since. The Fed meets next week, and while nobody expects a move now, their tone will likely signal to the market about the back half of the year.
I made this point on KIRO last month and it has held up: the buyers in this market made peace with the rate a long time ago. The ones holding out for 5.5% left the conversation last year. What remains is a smaller pool of serious buyers, which is why well-priced homes keep moving in days while the overpriced ones teach sellers expensive lessons.
55.7%
Sold in first
10 days on market
74.3%
Sold within
30 days on market
27 days
Avg. days on
market to sell
101.0%
Sale-to-list ratio
vs. asking price
Two Charts · The Early Summer Picture
The gold line is 2026 confirmed through May; the dashed extension is the June estimate. Historical years are shown for context.
If You’re Making a Move This Summer
If you’re selling, you are listing into the final stretch of peak velocity. A correctly priced home this month still meets a market where half of those homes that are selling, sell inside two weeks. That will likely not be true in late July. It never is. If your plan says “sometime this summer,” the front half of summer beats the back half, and the gap can be wider than people expect.
If you’re buying, a Pulse reading drifting toward neutral is working in your favor. Escalation wars thin out as momentum cools, contingencies come back to the table, and rates near 6.5% are keeping the casual “always looking” buyers on the sidelines. The formula I gave buyers in the spring hasn’t changed. Full underwriting rather than a pre-approval letter, a clear scope on neighborhoods and trade-offs, and the ability to move inside 48 hours when the right house surfaces.
If you’re weighing a move this summer, buying or selling, reach out. We’ll sit down, look at your goals and timing against the data, and create a custom tailored plan of action for you.
— Anton
Anton K. Alexander is a Broker with Elev8 Realty Group at Compass.
17+ years in Seattle real estate. $700M+ in career sales representation.